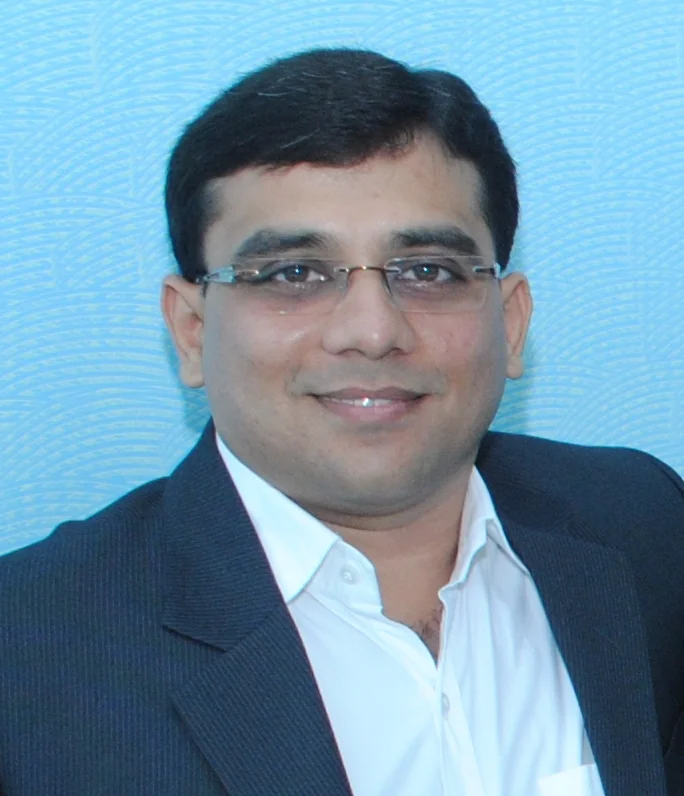
BCAS President CA Kinjal Shah’s Message for the Month of October 2026
Judgement in a Changing Profession
October is one of those months when the intensity of professional life becomes particularly visible. tax compliances, audit planning, quarterly closures, client expectations and regulatory developments converge, leaving little room for error or superficial judgement.
World Mental Health Day on 10 October is also relevant to the CA profession. In a profession where deadlines, client expectations and long working hours are part of everyday practice, mental well-being is closely linked to professional judgement and quality of work. Firms that encourage realistic workloads, effective delegation and adequate review time are not merely supporting employee well-being; they are strengthening professional quality.
Reading Between the Tax Numbers
The latest tax numbers provide the backdrop. As of September 17, 2026, net direct-tax collections stood at ₹12.1 lakh crore, up 13% year-on-year. Advance-tax collections rose 16.18% to ₹5.22 lakh crore, while corporate advance tax increased 18.09% to ₹4.16 lakh crore. Securities Transaction Tax collections rose sharply by 52.9% to ₹42,000 crore.
These are more than collection statistics; they reflect the continuing formalisation and digitisation of India’s economy, stronger compliance and growing economic activity.
For Chartered Accountants, the important question is what these numbers tell us about our changing profession.
From Compliance to Interpretation
A growing tax base and sophisticated information systems are changing expectations from professionals.
The CA’s value can no longer be defined merely by preparing financial statements, calculating tax or completing compliance requirements. Increasingly, stakeholders expect us to interpret information, identify risks, challenge assumptions and provide judgement.
The 18.09% growth in corporate advance tax invites deeper questions: what is driving corporate profitability, are earnings sustainable, do cash flows support reported performance, and what risks could emerge in the coming quarters?
The sharp increase in STT reflects the scale and dynamism of India’s capital markets, creating opportunities while demanding stronger understanding of transactions, taxation, governance and risk.
Corporate Accountability and Audit
The debate around the Corporate Laws (Amendment) Bill brings the question of professional judgement into sharper focus. The proposed exemption from mandatory audit for prescribed classes of private companies raises an important issue: how do we balance ease of doing business with corporate accountability?
There is a legitimate case for proportionality, as companies differ in size, ownership and stakeholder significance. But the discussion should not be reduced to whether an audit is “necessary” or “unnecessary”. The relevant question is what purpose independent assurance serves, and where it creates value.
The profession should engage with regulatory reform, supporting proportionate regulation while articulating where independent assurance contributes to transparency and accountability. Our credibility will depend on showing that our position rests on evidence and public interest, not self-interest.
Dialogue with Regulators Matters
BCAS continues to strengthen its institutional engagement with regulators. During the month, along with CA Chirag Doshi, Chairman of the 4i Committee, and CA Himanshu Kishnadwala, Past President, BCAS, I met senior officials of the Serious Fraud Investigation Office, including Mr Love Kumar, Additional Director, and Ms Sawni Dikshit, Joint Director, and also met Mr Nitin Gupta, Chairperson, National Financial Reporting Authority.
Such interactions matter because the relationship between the profession and regulators should extend beyond compliance and inspection. Constructive dialogue helps regulators understand the practical consequences of regulatory requirements while enabling the profession to appreciate their objectives. Good regulation should not merely impose obligations; it should also create clarity, consistency and accountability.
Digital Evidence and Financial Integrity
The growing sophistication of money laundering, financial fraud and cross-border financial crime makes financial transparency important. The 18th BRICS Summit in New Delhi, with its focus on illicit financial flows and terrorist financing, highlights the need for stronger cross-border information sharing. For Chartered Accountants, this reinforces the importance of AML and KYC discipline, transaction scrutiny and the integrity of financial information.
The Bankers’ Books Evidence Act, 2026, replacing an 1891-era law, reflects the shift of financial records to electronic, digital and cloud-based environments. For Chartered Accountants, this is more than a legal development; it reinforces an important professional principle, that financial information must be traceable, reliable and capable of standing up to scrutiny. As records move across cloud platforms and automated systems, documentation, access controls and audit trails become integral to professional work.
Tomorrow’s professional must understand not only what a number says but also where it came from, how it was generated and whether it can be trusted.
AI: More Efficiency, Greater Responsibility
Artificial intelligence is changing how professional work is performed, assisting with research, reconciliations, document review and data analysis. But an AI-generated output is not audit evidence merely because it appears plausible.
Professionals must understand the source data, limitations of the tool, parameters applied and procedures required to validate the output, and firms will need clear protocols covering confidentiality, documentation and accountability.
As routine procedures become automated, professional scepticism becomes more important, not less. The future CA may perform fewer repetitive procedures but will be expected to exercise greater judgement over the reliability of automated outputs.
The Profession Ahead
I believe the profession must focus on three priorities.
First, protect the quality of professional judgement. Workload pressures must not compromise review, delegation or professional scepticism. Firms need an environment where professionals have time to think, not merely to finish.
Second, adopt technology without outsourcing accountability. AI and automation should make professional work smarter and deeper, never a substitute for responsibility.
Third, engage with regulatory reform, supporting simplification where it improves the business environment while articulating, with evidence, where assurance and accountability remain essential.
India’s tax numbers demonstrate the scale of economic formalisation, digital regulation is reshaping financial information, and AI is changing professional work. Yet one principle remains constant: the value of a Chartered Accountant does not lie in producing an answer; it lies in standing behind that answer.
Our challenge is not to handle more data, technology or regulation, but to ensure that, amid this change, we continue to bring what no system can fully automate: independent judgement, professional scepticism and the courage to ask the right question.
That is where the future value of our profession will be built.